Bitcoin did not emerge from an academic discussion. It was born in the midst of a crisis, and this crisis has a name and a date.
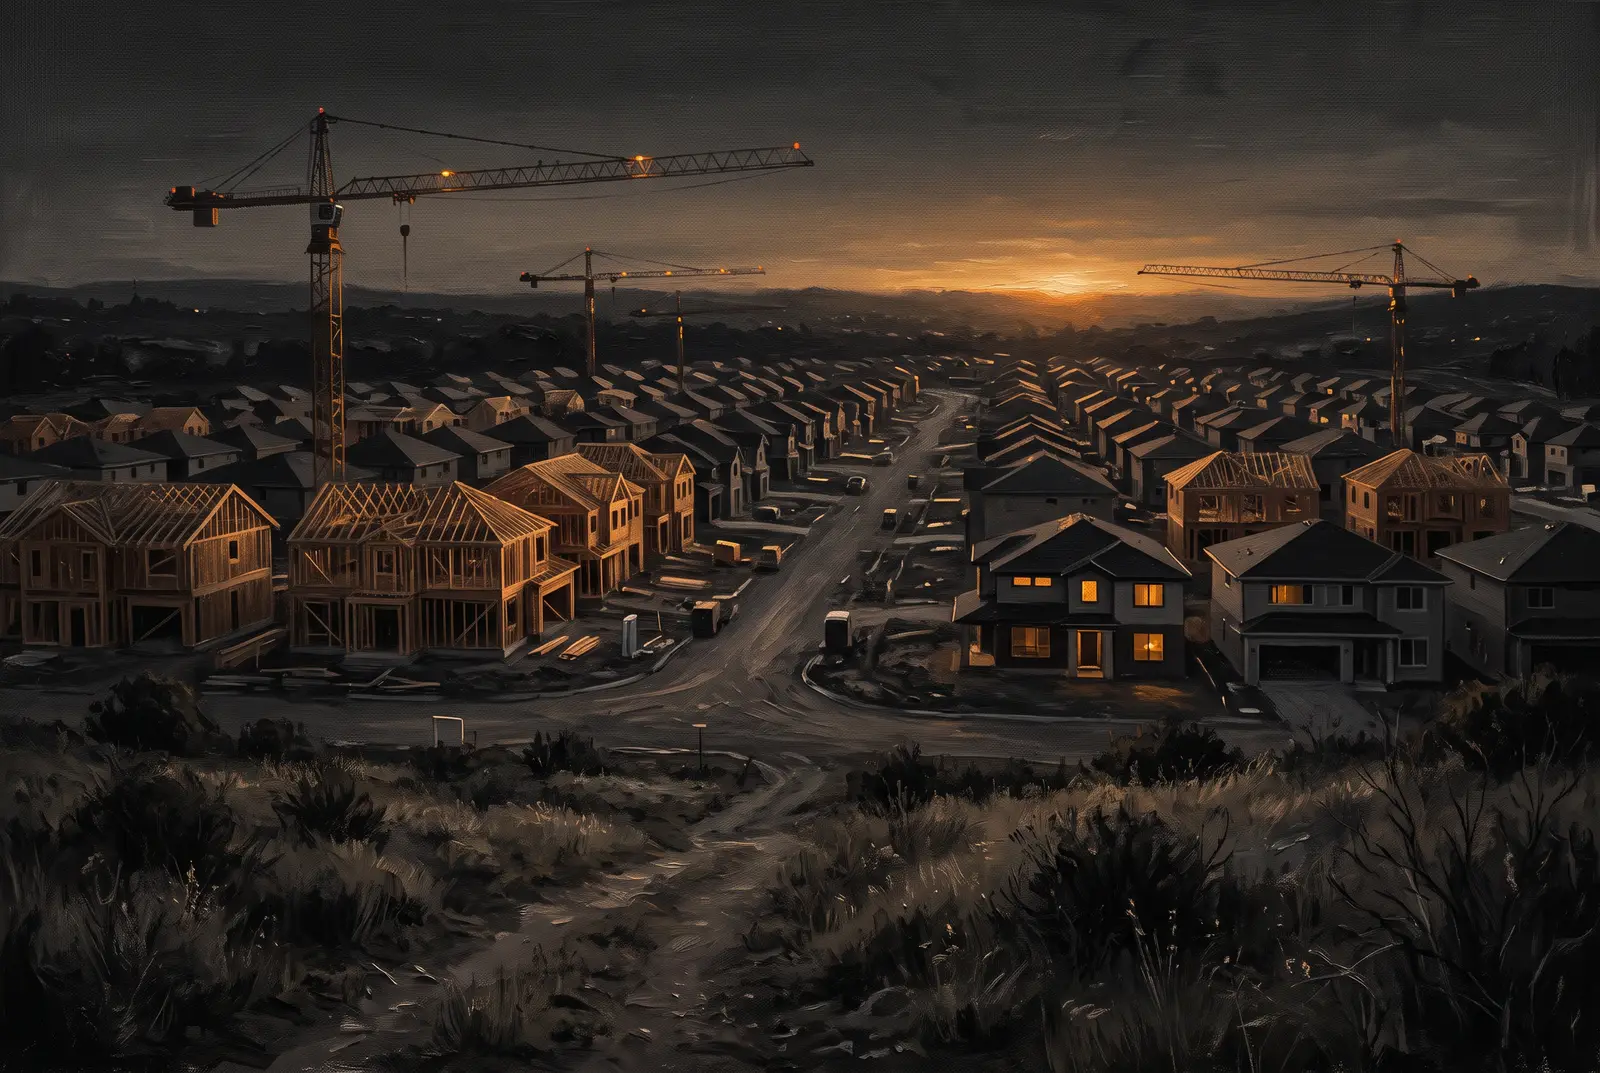
The story begins in the United States, with low interest rates and easy mortgage credit. Financing a house became so cheap that demand exploded, and prices kept rising for years. As prices rose, everyone seemed to be right: buyers made profits, lenders had collateral that appreciated on its own, and skeptics appeared pessimistic. It was in this climate that subprime loans became popular, granted to borrowers with little or no proven ability to pay, often with low installments in the first years and a jump later on.
The second ingredient was packaging. Instead of holding onto these loans, banks bundled them by the thousands and sold the package as a security, with rights to the payment flows from families. Packages were sliced into tranches, tranches were repackaged into new packages, and at the end of the chain was a paper that almost no one could truly analyze. Rating agencies stamped much of this mountain with the highest rating. Pension funds, municipalities, and banks worldwide bought them.
The third ingredient was leverage. Institutions operated with a minimal fraction of their own capital for each real of exposure, which multiplies profit as prices rise and destroys the institution in a small downturn.
In 2006 and 2007, real estate prices stopped rising and began to fall. Installments rose, defaults rose along with them, and the securities backed by these mortgages became papers without a price — not because they were worth little, but because no one could say what was inside them. In September 2008, Lehman Brothers, an investment bank with over 150 years of history, filed for bankruptcy. Interbank credit froze: none of them knew which of the others was insolvent, so they all stopped lending to each other.
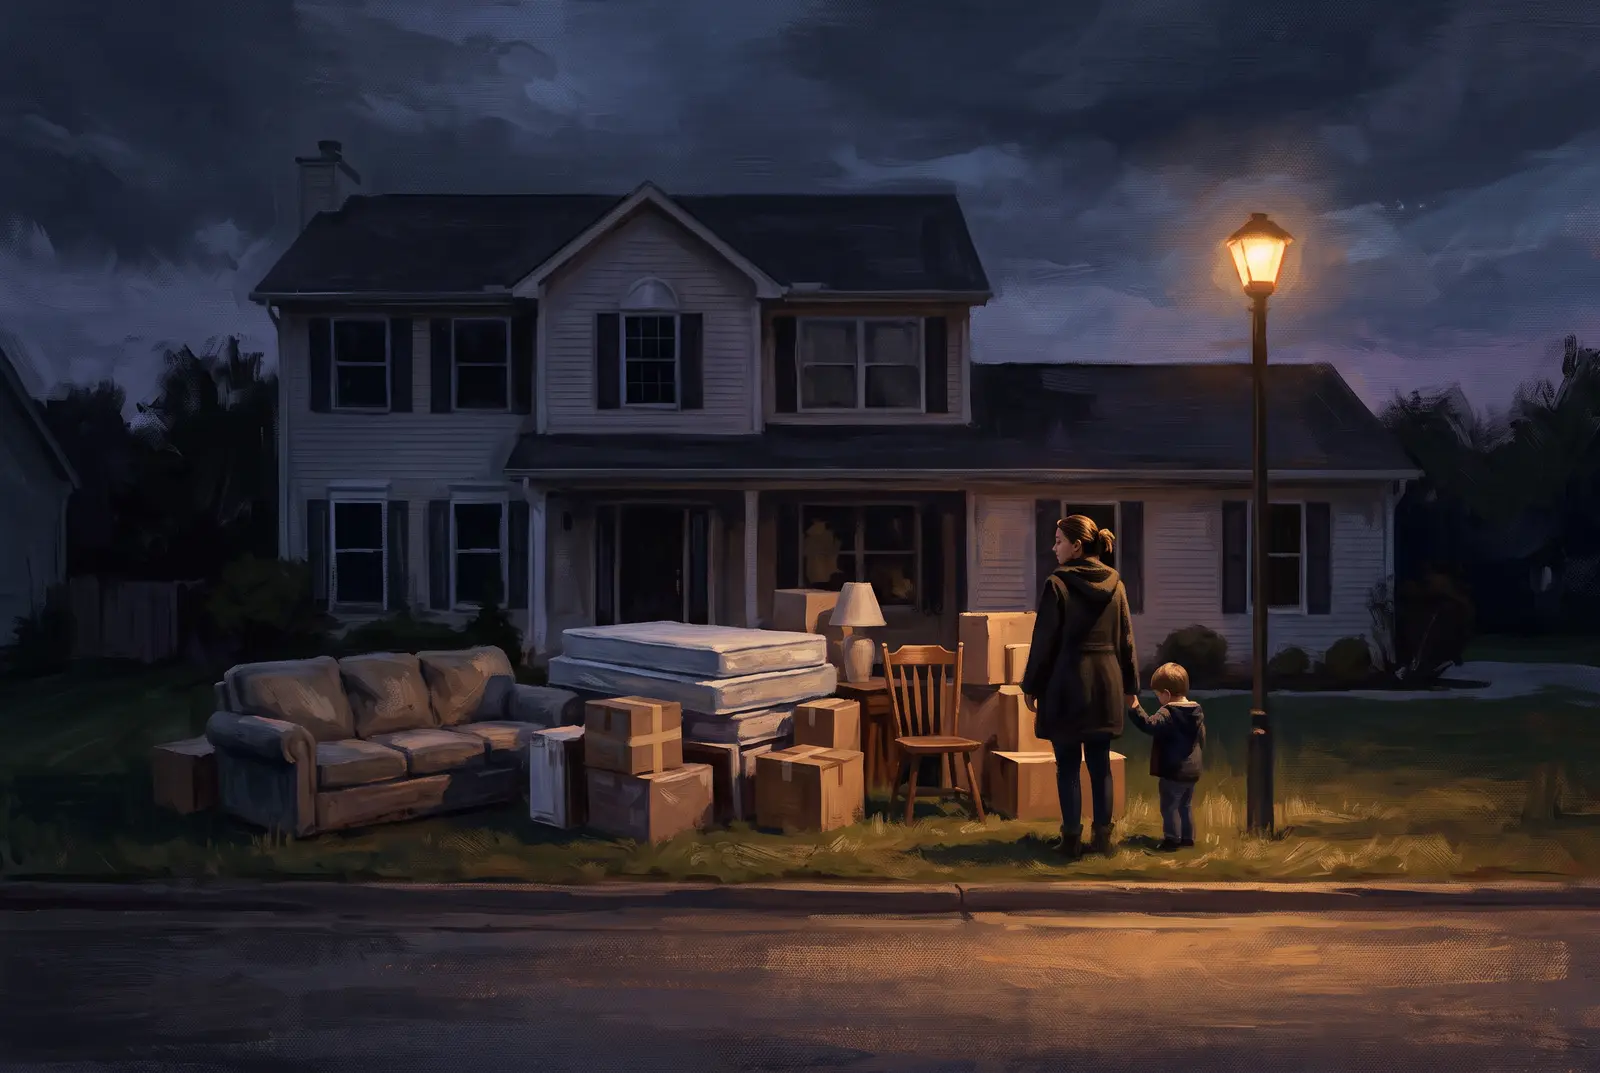
The response came from the State. Banks and insurers deemed too big to fail were bailed out with public money, in programs amounting to hundreds of billions of dollars, and central banks spent years buying assets and expanding balance sheets to support the system. The justification — to avoid an even greater collapse — is defensible and continues to be debated. But the practical result was hard to swallow for outsiders: millions of families lost homes and jobs, while institutions that had taken the risks were kept afloat with everyone's money, and savers paid the price through currency devaluation.
It is in this scenario that the document appears. On October 31, 2008, five weeks after Lehman's collapse, someone under the name Satoshi Nakamoto published a nine-page paper on a cryptography mailing list: "Bitcoin: A Peer-to-Peer Electronic Cash System." The first line of the abstract proposes a version of electronic money that allows payments directly from one party to another without going through a financial institution.
On January 3, 2009, the first block of the network was created. Inside it, in a field that accepts free text, Satoshi recorded a phrase: "The Times 03/Jan/2009 Chancellor on brink of second bailout for banks" — the headline of the British newspaper The Times that day, about the finance minister on the brink of a second bailout for banks.
That phrase serves two functions. One is technical: it proves that the block was not created before that date. The other is a declaration of intent, leaving no doubt about what was being proposed and against what.
It is important to be precise about what Bitcoin is and what it is not. It is not a government plan, nor a promise to make you rich, nor a solution to everything that was wrong in 2008. It is a technical proposal for a specific question that this entire module has been building: is it possible to have money that is verifiably scarce, that anyone can use without asking for permission, and whose rules cannot be changed unilaterally?
The answer to this question — how it works, why it works, and where it still encounters obstacles — is the subject of the next module.